TL;DR

Get business pricing on office and shipping supplies
- Business-only prices and quantity discounts
- Tax-exempt purchasing
- Multiple users, one account, clear invoices
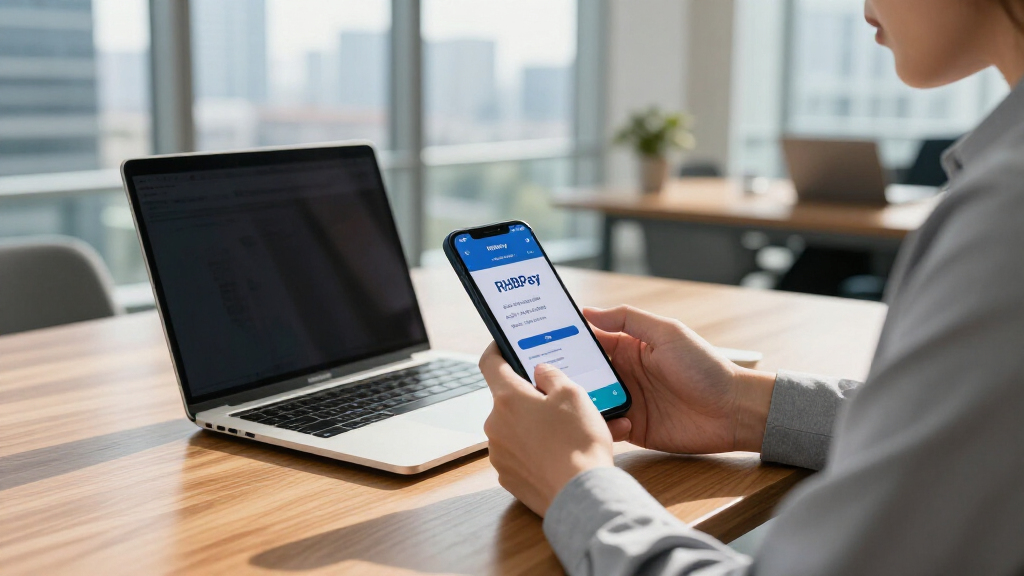
RHB Bank has introduced RHBPay, the first integrated payment gateway owned by a Malaysian bank. This marks a significant step in digital payment infrastructure, with potential impacts on merchants and consumers.
RHB Bank has officially launched RHBPay, a comprehensive, bank-owned integrated payment gateway in Malaysia. This development aims to streamline digital transactions for merchants and consumers, positioning RHB as a key player in Malaysia’s evolving fintech ecosystem. The launch signifies a strategic move by RHB to deepen its digital banking capabilities and capture a larger share of the rapidly growing digital payments market.
RHBPay is described as Malaysia’s first integrated payment gateway owned and operated by a bank, providing a seamless platform for merchants to accept various digital payment methods, including credit cards, e-wallets, and bank transfers. The service is designed to integrate with existing merchant systems, offering real-time transaction processing and enhanced security features.
According to RHB Bank, the platform aims to reduce reliance on third-party payment providers, potentially lowering transaction costs for merchants. The bank also emphasizes the user-friendly interface and robust fraud protection measures embedded within RHBPay. The launch was announced in March 2024, with initial rollouts targeting small to medium-sized enterprises (SMEs) across Malaysia.
While RHB has not disclosed specific financial targets or user adoption numbers, industry experts see this move as part of a broader trend among Malaysian banks to develop proprietary digital payment infrastructure amid increasing competition from fintech firms and e-wallet providers.
Strategic Impact on Malaysia’s Digital Payment Ecosystem
The launch of RHBPay is significant because it marks the first time a Malaysian bank has introduced a fully integrated, bank-owned payment gateway, potentially setting a new industry standard. This development could lead to increased competition among banks and fintech companies, fostering innovation and possibly driving down costs for merchants and consumers.
For RHB, this move enhances its digital banking offerings, allowing it to retain more control over transaction data and reduce dependency on external payment processors. It also positions RHB as a more comprehensive financial services provider, potentially attracting new customers seeking integrated digital solutions.
Overall, RHBPay could influence the future landscape of digital payments in Malaysia, encouraging other banks to develop similar infrastructure and possibly accelerating the country’s cashless economy goals.
NFC payment terminal for small business
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Growing Interest in Digital Payment Infrastructure in Malaysia
Interest in digital payments in Malaysia has been rising sharply, driven by increased smartphone adoption and government initiatives promoting a cashless society. Search interest for terms related to digital payment gateways and fintech solutions has spiked in recent months, reflecting heightened industry and consumer attention.
Prior to this launch, most digital payment solutions in Malaysia relied heavily on third-party providers like e-wallet firms and international payment processors. The move by RHB to develop its own integrated platform aligns with a broader industry trend among Malaysian banks to build proprietary systems to better serve their customers and compete with emerging fintech players.
While the exact trigger for RHB’s decision remains unconfirmed, market analysts suggest that the bank aims to capitalize on the momentum of digital transformation and the increasing demand for integrated, secure payment solutions.
As an affiliate, we earn on qualifying purchases.
Unconfirmed Details and Potential Challenges for RHBPay
It is not yet clear how quickly RHBPay will achieve widespread adoption among merchants or how it will compare in cost and performance to existing third-party solutions. Details about the platform’s scalability, security features, and integration capabilities are still emerging. Additionally, the response from competitors and fintech firms remains uncertain, as does the regulatory environment’s influence on the platform’s growth.
Further developments are needed to understand whether RHBPay will become a dominant player or remain a niche offering within Malaysia’s digital payments ecosystem.
credit card and e-wallet payment terminal
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Next Steps for RHBPay and Market Adoption
RHB Bank is expected to roll out RHBPay gradually, initially targeting SMEs and key merchant segments. Monitoring user adoption rates, merchant feedback, and transaction volumes over the coming months will be crucial to assess its success. The bank may also introduce additional features or expand the platform’s reach to larger enterprise clients.
Industry observers will watch for responses from competitors, including other Malaysian banks and fintech firms, which may develop similar proprietary solutions or form strategic alliances to counter RHB’s initiative. Regulatory updates or government policies supporting digital infrastructure could also influence RHBPay’s trajectory.
bank-owned payment processing device
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
Key Questions
What makes RHBPay different from existing digital payment solutions in Malaysia?
RHBPay is the first integrated payment gateway owned and operated by a Malaysian bank, offering a seamless, secure platform that integrates with merchant systems and supports multiple digital payment methods, potentially reducing costs and increasing control for merchants.
Who can use RHBPay initially?
The initial rollout targets small to medium-sized enterprises (SMEs) across Malaysia, with plans to expand to larger businesses and other sectors in the future.
Will RHBPay replace third-party payment providers?
While RHBBank aims to promote RHBPay as a primary solution for its customers, it is unclear whether it will fully replace third-party providers or coexist alongside them, depending on market acceptance and competitive responses.
What are the potential benefits for merchants using RHBPay?
Merchants could benefit from lower transaction fees, faster settlement times, integrated security features, and better data control, which may improve operational efficiency and customer experience.
Source: primary
Halloween Picks
halloween
As an affiliate, we earn on qualifying purchases.